


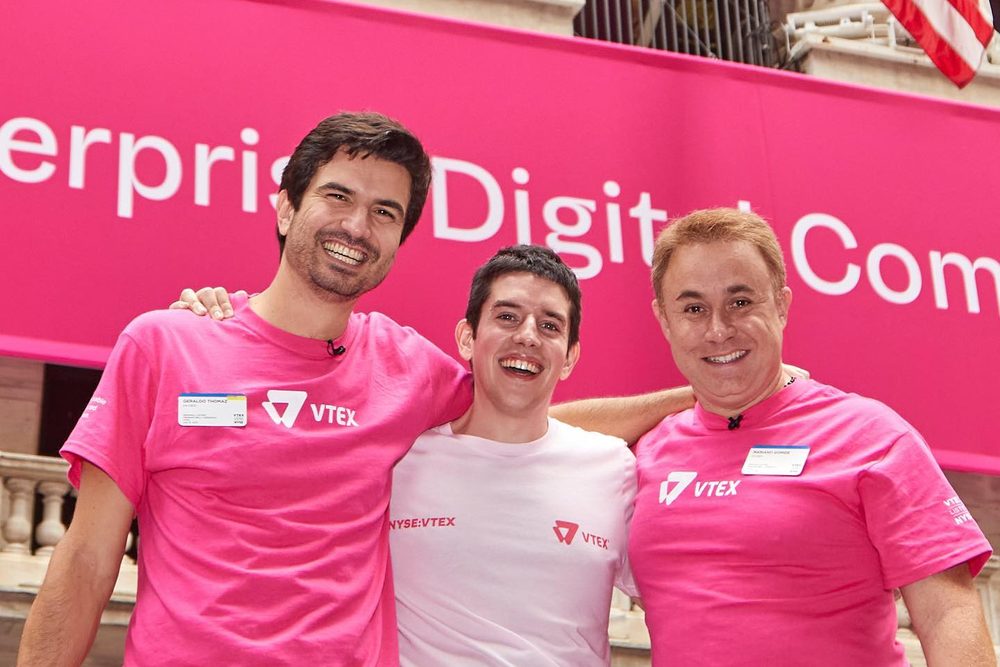
I spent nine years at VTEX and lived through its NYSE IPO from the inside. That's where I learned a prospectus is the one document where a company is FORCED to tell the truth about itself, with auditors, lawyers and the SEC reading along.
When Anthropic filed its S-1, I read the whole thing.
It's the most important document of the year for anyone who builds software. For the first time someone shows, with audited numbers, what it costs and what it pays to put AI to work.
It describes, almost line by line, the world deco bet everything on two years ago.
Every number comes from the S-1 filed with the SEC unless I say otherwise. These are the five passages that got me.
1. $80.7B in accounting losses and $3.9B in cash generated in the half
The easy headline is "Anthropic loses $80.7 billion in six months".
Of that 80.7, $72.4 billion is mark-to-market on convertible notes, derivatives and SAFEs. Translation: paper investors bought when Anthropic was worth far less is now worth MUCH more, and accounting books that difference as a loss. Nobody wired that money anywhere.

Take the paper out and you get +8% operating margin in Q2 (−152% a year earlier) and $3.9 billion of cash generated by operations in the half.
A lab training the biggest models on the planet already pays for itself operationally.
2. The GPU bill stopped eating the company
In 2024, Anthropic spent $6.50 on compute for every $1 of revenue. In H1 2026, it spent 55 cents.

In Q2, revenue grew 1,368% year over year. Compute spend grew 300%. Working from the cost-of-revenue note, implied gross margin for the half lands near 85%.
85% is a software margin. Anyone who swore AI would forever be a thin-margin business held hostage by NVIDIA needs a new argument.
3. Agents consume a lot of tokens
80% of H1 revenue is token consumption, and the S-1 shows who consumes them. Claude Enterprise users who don't use Claude Code spend under $75 a month, while the top 5% of Claude Code users spend about 20 times that.

A conversation uses a few thousand tokens. An agent that reads the repo, runs the tests, opens the PR, gets yelled at by CI and tries again uses millions, because it's WORKING. That's why customers paying over $100k a year jumped from about 1,500 at the end of 2025 to more than 11,900 in September.
The prospectus's biggest risk lives in that 80%
80% of revenue is tokens, and tokens are exactly the line on the invoice every CFO in the world is incentivized to cut. Every company spending heavily on Claude, deco included, has someone staring at that bill every month.
That creates an obvious business for a thousand startups: sit in the middle, swap Anthropic's tokens for a Chinese open model ten times cheaper on the tasks where nobody notices the difference, and pocket the spread. People are already doing it, and many more will.

The S-1 itself admits it in plain words: demand for frontier models may decline if customers conclude that "less advanced, lower-cost" models are enough, and open-weight models may exert pricing pressure.
Why do I still bet on Anthropic? Because in agent work what counts is cost per delivered task. A model ten times cheaper that botches the PR three times and breaks checkout ends up MORE expensive. And Anthropic itself attacks the spread from above, since Opus 5.5 cut cost per task by about 40%.
But the risk is real. On commodity tasks, the spread will get eaten fast. Anthropic will have to prove, quarter after quarter, that the long, hard work stays with Claude.
4. Claude writes Claude
In the section called "Closing the loop", the S-1 says that in September 2026 over 90% of contributions to Anthropic's codebase were written by Claude. Code volume per engineer per day is 45× the 2024 level. And the team grew far less than the business.

That's $6.6 million of revenue per employee over the last twelve months, up from $1.4 million a year earlier.
It's the first large company to show on its books what happens when the product builds the product.
5. Anthropic tied itself to the mast
Ulysses asked to be tied to the mast because he knew he'd hear the sirens and didn't trust himself in the moment. Anthropic's capital structure does the same thing, in its charter.

It goes public as a Public Benefit Corporation. A Long-Term Benefit Trust elects most of the board. The seven co-founders pledge 80% of their equity to philanthropy. And 5% of shares go to a public benefit fund, which gets another 2% every time the stock rises 50%.
I find this structure brilliant. When you sell to more than half the Fortune 500, you're selling TRUST, and this is the written guarantee. Integrity written into the charter.
Why this IPO matters even if you never buy a share
AI economics left the guesswork zone
Until yesterday, a frontier lab's margins, compute costs and retention were podcast gossip. Now they're audited numbers. Every investor, board and CFO will calibrate what good looks like from here.
Solid ground for builders
A supplier with ~85% gross margin and 900% NRR isn't going to vanish, or double token prices overnight. Anyone building products and services with Claude just gained predictability.
The AI curve in anyone's hands
The fastest-growing company in software stops being a privilege of funds. On Nasdaq, as ANT, anyone can own a piece of it.
Brazil is already on this curve
The Anthropic Economic Index ranks Brazil as Claude's 3rd-largest market, behind only the US and India. We already use it. What's left to decide is whether we watch or lead.
The S-1 is preliminary: price range, share count and offering size are blank. Press reports (Fortune) talk about a $1.5–2T valuation and a debut around Thanksgiving. The last private round, in May, was at $965B. The prospectus is honest about risks: compute committed 12 to 18 months ahead, and margins that may tighten as new capacity comes online. This is not investment advice.
What we learned running Claude Code at scale
At deco, almost all engineering work goes through Claude Code, and since August every agent we run sits on top of it. Each task gets an isolated sandbox, becomes a PR with a deploy preview and, after deploy, stays monitored.

Running that loop hundreds of times a day taught us five things.
The bottleneck now is proving it worked.
Claude writes the code. A PR is good when you can prove it works, with tests, a visual diff against production and performance metrics. These days we spend more energy building verifiers than writing prompts.
Skills and MCP beat giant prompts.
Knowledge packaged as skills the agent loads when it needs them, and system access through MCP. The same agent serves many customers, and you can audit what it knows.
One sandbox per task. Always.
Isolation solves half the security problems and nearly all the concurrency ones. Hundreds of agents in parallel only work because none of them can see the others.
Measure cost per delivered task.
Cheap tokens on an agent that fails are expensive. Our control number is the cost of each task that becomes an approved PR, and it drops with every model generation. The S-1 itself says Opus 5.5 cut cost per task by about 40% versus Opus 5.
Use subscriptions whenever you can.
Internally, deco moved from per-token billing to subscriptions, and the team's AI cost dropped 3 to 5 times with no loss in productivity. Same Claude Code, fixed cost per person.
Ring the bell, Anthropic
I've seen up close what an IPO does to a company. It forces everyone to see what the company already is.
Anthropic's S-1 forces the market to see that AI agents are already a huge business, one that pays for itself operationally and is still at the very start of the curve.
For anyone building software, the job now is turning tokens into results you can prove. And Brazil, Claude's 3rd-largest market in the world, has everything it needs to lead this story.
Congratulations to the Anthropic team, and thank you for Claude. We'll keep spending more and more.


